 ID
 EN
 FR
 ES
 KO
 PT
 ZH
 AR
 FA
 RU
 NL
 MS
 VI
 PH
 TH


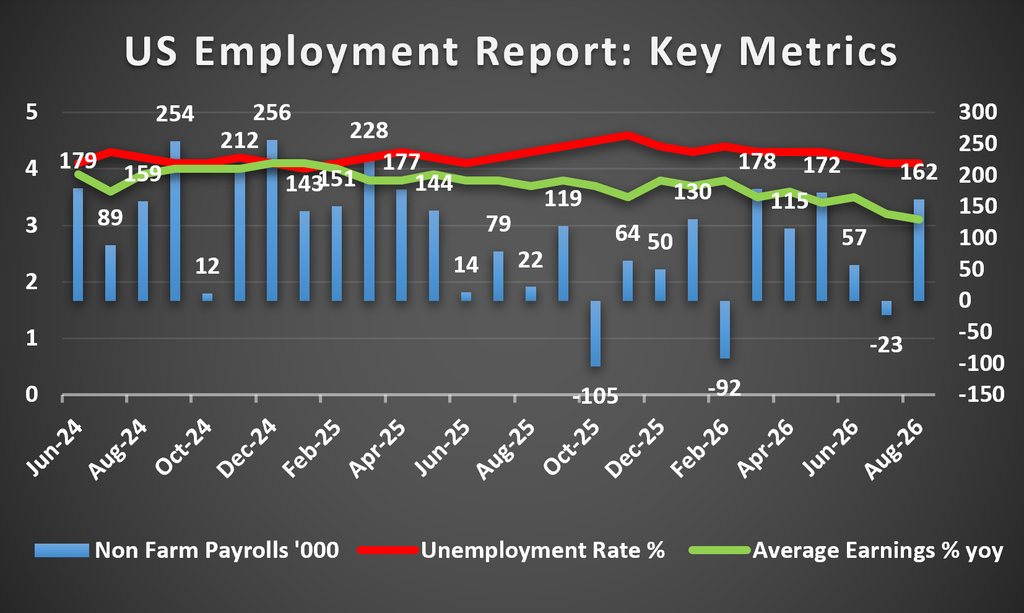
USD – September’s US employment report to rock the markets
The USD is about to end the week in the greens for a second time in a row, despite some losses today. Overall the dominance of the USD in the FX market seems to be maintained.
US treasury yields seem to continue their upward trajectory, while the market’s expectations for the Fed’s intentions continue to lean on the hawkish side, providing support for the USD.
On a macroeconomic level though things are to get more interest ing the coming week for USD traders. We make a start by noting that coming Wednesday we get the PCE rates for August and GDP rates for Q2 and a possible acceleration of the rates could provide some support for the US Das it would imply a faster growth rate for the US economy and a possible boost of inflationary pressures in the US economy.
Yet the highlight of the week is expected to be the release of the US employment report for September coming Friday. A looser than expected US employment market could weigh on the USD, while at the same time provide support for gold’s price and US equities.
On the flip side a possibly tighter than expected US employment market could enhance the market’s expectations for the Fed to keep tightening its monetary policy and thus providing support for the USD and weigh on gold’s price and US equities.
GBP – UK’s Q2 GDP rate in focus
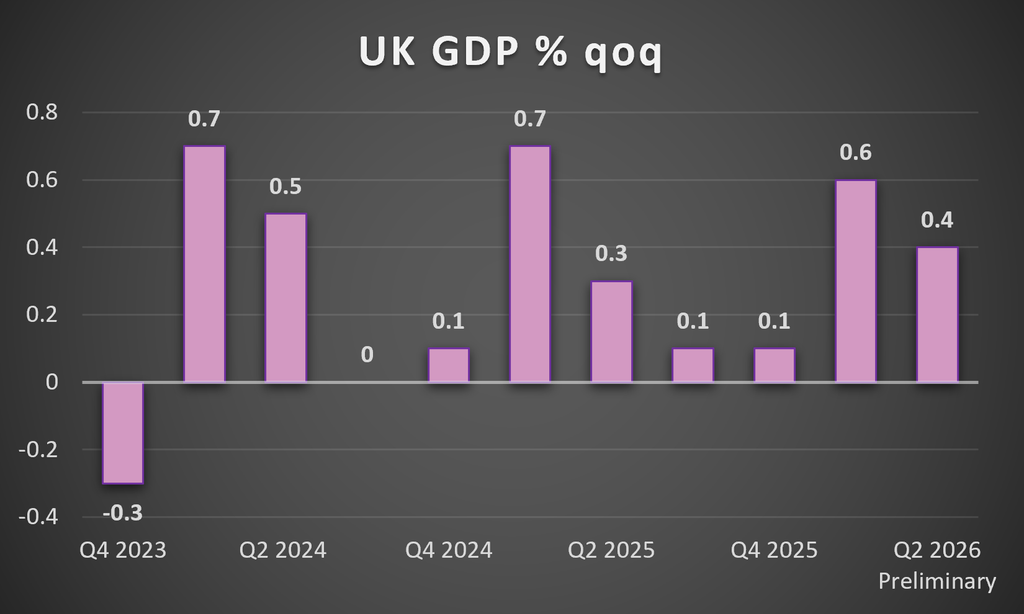
Pound traders are expected in the coming week to focus on UK fundamentals and the release of UK’s GDP rate for Q2.
On a political level, we note the difficulties faced by UK PM Burnham’s on a fiscal level. The UK government’s effort to avoid the increase of taxes, which could politically entrap it, seems to be come increasingly more difficult. Overall a possibly restrctive fiscal policy could weigh on the GBP.
On a monetary level, the market’s expectations for the BoE are hawkish as the bank is expected to hike rates in the November meeting. BoE Governor Andrew Bailey’s comment that should energy prices remain high, the bank may have to raise rates, tends to corroborate the market’s hawksih expectations. Overall should the market’s hawkish expectations be maintained we ma ysee the pound getting some support.
On a macroeconomic level, we highlight the release of the UK’s final GDP raqte for Q2. Given the low levels of growth for the UK economy a possible acceleration of the rates could provide some support for the GBP in the FX market.
JPY – Tankan Q3 indexes and Tokyo’s September CPI Rates
Despite JPY losing ground throughout the week, it regained the initiative against the USD today.
On a fundamental level we note that the weaker JPY becomes, the possibility of another market intervention operation by Japan to the Yen’s rescue, possibly in coordination with the US, tends to increase.
On a monetary level, BoJ remains hawkish yet the market seems to distrust the bank. It’s characteristic that JPY got some support today as Finance Minister Katayama defended the independence of BoJ and reiterated Tokyo’s commitment to Yen stability.
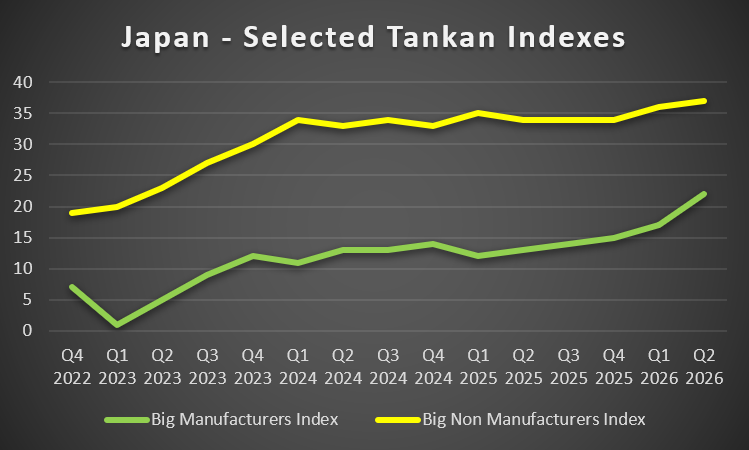
On a macroeconomic level, we note from Japan the release of the Tankan indexes for Q3. A possible rise of the indicators’ readings for the manufacturing and services sectors could provide some support for the JPY, as it may imply a widening of economic activity in the Japanese economy.
Also we note the release of Tokyo’s CPI rates for September as the density of the population of the megacity, allows its CPI rates to act as a precursor for Japan as a whole. A possible slow down of the rates could weigh on JPY as it may raise some doubts about BoJ’s narrative for the necessity of a tightening of its monetary policy given high inflation.
EUR – September’s preliminary HICP rates to move the EUR
The common currency may be in a tight spot.
On a political level, EUR traders are still digesting the results of the latest German state elections, which may still be shaking the Chancellery of Friedrich Merz. Further more we highlight the possibility of the US banning exports of oil, a scenario that may weigh substantially on growth in the Euro Zone and boost inflationary pressures in the Euro Zone as oil prices may get even higher.
On a monetary level, we note the market’s expectations for the ECB to keep rates unchanged inn October and continue hiking ratesin its December meeting. Overall the market’s expectationsfor the ECB are leaning on the hawkish side. We still see the possibility of the bank being forced by high inflation rates to deliver a rate hike in the October meeting.
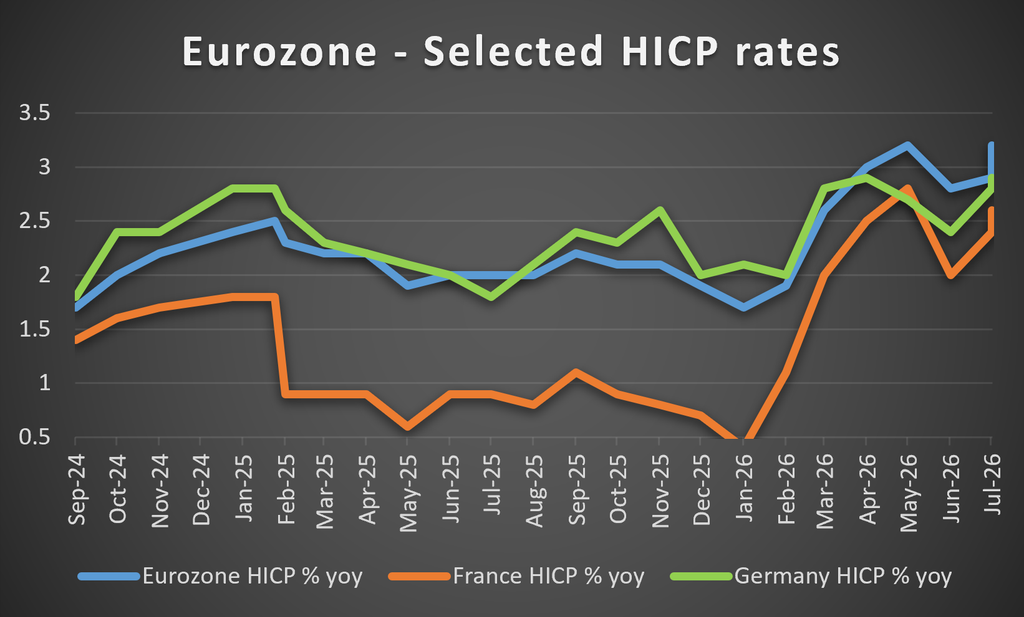
On a macroeconomic level, we highlight the release of the preliminary HICP rates for September. Inflation is currently higher than ECB’s 2%yy target and should it accelerate even further, possibly beyond market expectations, the release may add even more pressure on the ECB to tighten its monetary policy, thus supporting the EUR.
Vice versa a possible slow down of the rates may ease market worries for inflation in the Euro Zone and weigh on EUR.
AUD – RBA expected to hike rates
Aussie traders are expected to keep a close eye on the release of RBA’s interest rate decision on Tuesday’s Asian session.
The bank is widely expected to hike rates by 25 basis points and AUD OIS imply that the market has almost fully priced in such a scenario. Yet a mere rate hike may not cut it for the Aussie.
The market expects the bank to hike rates again in December, implying a hawkish predisposition. Hence should the bank hike rates as expected and accompany the decision with a possibly hawkish forward guidance signalling that more monetary policy tightening is in the pipeline, we may see the Aussie getting some support as the release could validate the market’s expectations.
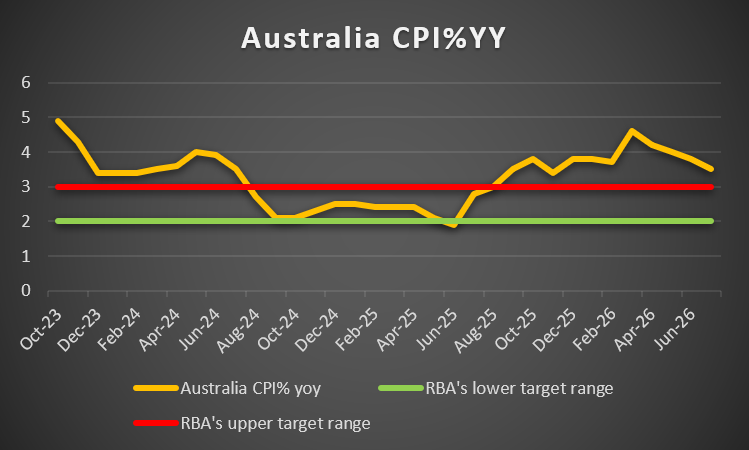
It should be noted that at the current stage inflation is above RBAs’ upper boundary of tolerance, yet is slowing down.
Hence, should the bank fail to sound hawkish enough, we may Aussie traders being disappointed, the market being forced to dial back its hawkish expectations and the rate hike turning into a dovish rate hike, weighing on AUD.
CAD – Canada’s July GDP rates to be released
The Loonie continued to weaken against the USD, maybe being victimized by USD aggressiveness in the FX market more than other currencies.
It should be noted that even today, the USD is weakening but to a lesser extent against the CAD, than against other currencies.
On a fundamental level, the tensions in the USCanadian trade relationships are ongoing and weighing on the Loonie. Any further escalation of the tensions in the US-Canadian trade relationships could weigh further on the Loonie.
On a monetary level, the market expects BoC to hike rates in the October meeting and is in doubt of another rate hike in the December meeting. Overall, the market ‘s expectations for the BoC seem to be leaning on the hawkish side, yet not at the pace of the Fed’s monetary policy tightening.
The interest rate differential outlook between the Fed and the BoC tends to weigh on the CAD at the current stage.
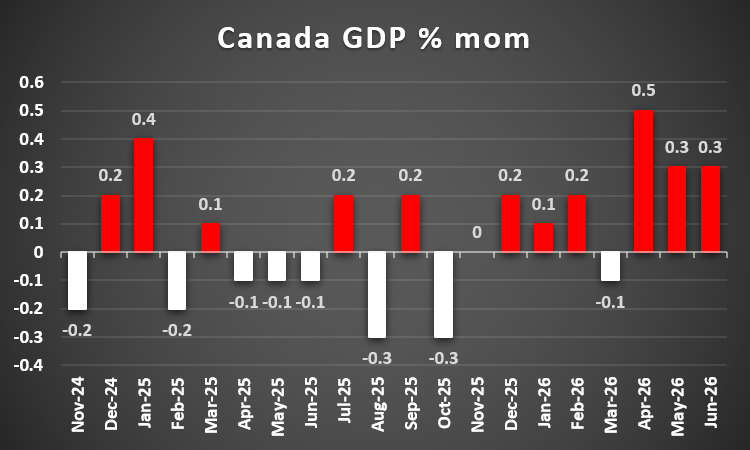
On a macroeconomic level, we note the release of Canada’s GDP rate for July next Wednesday and a possible acceleration of the rate could provide some support for the CAD as it would imply a faster than expected growth of the Canadian economy
Disclaimer:
This information is not considered as investment advice or an investment recommendation, but instead a marketing communication. IronFX is not responsible for any data or information provided by third parties referenced, or hyperlinked, in this communication.


