 ES
 EN
 FR
 KO
 PT
 ZH
 AR
 FA
 RU
 NL
 MS
 VI
 PH
 TH
 ID

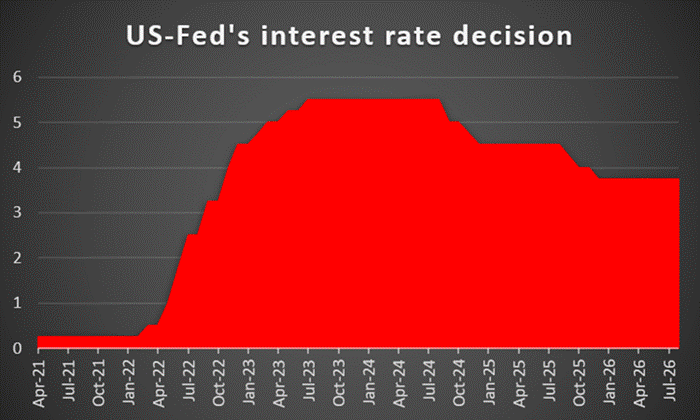
USD – Fed expected to remain hawkishly on hold
The USD seems about tio end the week in the reds for a second time. Markets are now focusing on the release of the Fed’s interest rate decision next Wednesday. Fed Fund Futures (FFF) imply that the markets expect the bank to remain on hold on Wednesday, yet at the same time they also expect the bank to hike rates in the December meeting. Overall, we expect the bank to remain on hold and given the inflationary pressures the bank may opt to maintain a hawkish tone in its forward guidance, given the inflationary pressures in the US economy, yet the easing of the US employment market may be advising some caution. Should the bank remain on hold and actually sounding hawkish enough to verify the bmarket’s expectations for a rate hike to come in its next meeting, we may see the USD getting some support, while US stock markets and gold’s price may head southwards.
Yet should the bank fail to sound hawkish enough, the market may be forced to ease its hawkish expectations and thus turn the decision into a dovish one, which could weigh on the USD and lift US stock markets and gold’s price. On a macroeconomic level, we note the relese of the US PCE rates, yet are not to affect the market’s expectations for the Fed’s decision as they are to be released on Thursday, nevertheless a possible faster than expected acceleration of rates could signal intensifying inflationary pressures, thus supporting the USD. Also, on Thursday we highlight the release of the US GDP advance rate for Q3. Should the rate acelerate beyond market expectations we ma ysee the USD getting some support, as it would be a signal of the US economy has grown at a faster than expected rate.
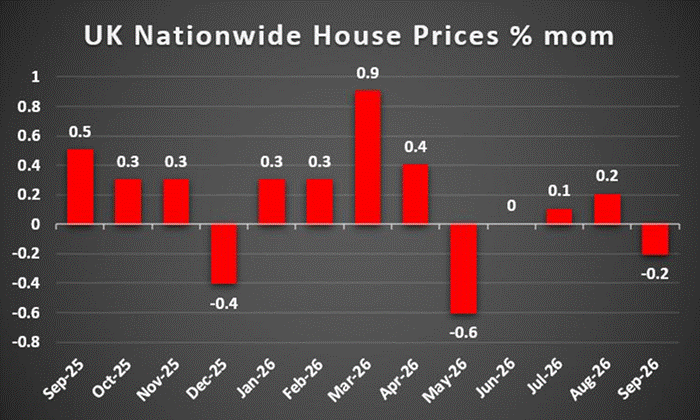
GBP – UK Government’s Autumn statement expected
The GBP seems to be about to close the week in the greens against the USD and the EUR, but not the JPY. With accelerating UK CPI rates for September, a faster GDP growth rate for August and a tighter employment market for the same month, convinced pound traders to buy the sterling. The calendar is rather empty of UK financial releases next week hence we expect the fundamentals to lead the pound in the coming week. On a monetary level, we note the market’s expectations for the BoE to hike rates in its November meeting. The market’s hawkish expectations tend to be supportive for the pound and actually the high energy costs, leave little rrom for Boe to maneuvre.
On a fiscal level, we highlight that UK Chancellor of the Exchequer John Healey, is to deliver the UK Autumn Budget next Thursday. The UK Government pledged for “growth in every postcode” and the question every one is asking is whether it will have to raise taxes to achieve it. A possible tightening of the UK Government’s fiscal policy, through the rise of taxes could weigh on the pound while conversely pledges for possibly increased fiscal spending could lift the pound. The UK government is in a rahter tight spot right now given its past promises and in the coming week is expected to be under the microscope of pound traders.
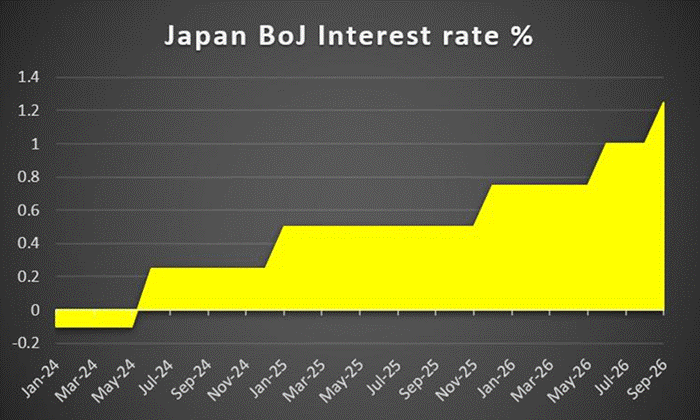
JPY – BoJ expected to keep rates unchanged
JPY is about to end the week in the greens against the USD, EUR and GBP being possibly the winner for the week in the FX market. On monetary level, we highlight BoJ’s interest rate decision next Friday, which may be the man event for JPY for the week. The bank is widely expected to remain on hold and currently JPY OIS imply a probability of 97.2% for the bank to rates at 1.25%. The bank is also expected to proceed with a rate hike in the December meeting. We expect the bank to remain on hold on Friday and issue possibly a hawkish forward guidance signalling its intentions to raise rates in its next meeting.
Japan’s CPI rates accelerated in September, beyond the banks’ inflation target of 2%yy, adding more pressure on BoJ to act as the risk of inflationary pressures surpassing the banks’ tolerance level, is now more than visible, fitting BoJ’s hawkish narrative. It’s characteristic how BoJ Deputy Governor Himino, even the day before the release, warned about the bank possibly moving too late in raising its interest rates, flagging the risk of high inflation. Overall we see the case for risks surrounding the event as being tilted to the bullish side for JPY. Also on a fundamental level we highlight JPY’s status as a safe haven, a factor that provided substantial support for JPY on Thursday, given the AI jitters in US equity markets.
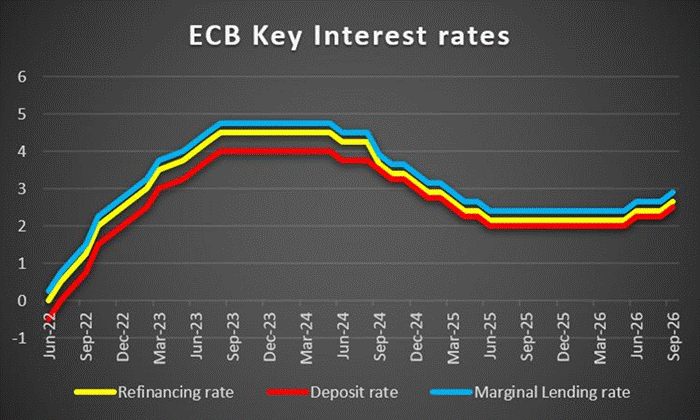
EUR – ECB to stand pat, yet may signal hikes to come
The common currency seems to be losing ground across the board. On a fundamental level the protests in France turned violent over the past weekend, shocking EUR traders, while there is a political unrest across the Zone, which generates uncertainty about its political outlook, both weighing on the EUR. On a macroeconomic level the drop of October’s preliminary PMI figures, signalling a slow down in the expansion of economic activity wasn’t helpful either. In the coming week we may get some interest as we get the preliminary HICP rates for October of France and Germany and Euro Zone’s preliminary GDP rates for Q3.
A possible acceleration of the prementioned rates could generate some support for the EUR, yet that remains to be seen. The highlight of the coming week for EUR traders is expected to be the release of ECB’s interest rate decision, on Thursday. The bank is widely expected to remain on hold and currently EUR OIS imply a probability of 90.6% for such a scenario to materialise. EUR OIS also imply that the market increasingly expects the bank to hike rates in December, signalling that the market considers the current monetary tightening cycle as still open.
Should the bank signal more hikes to come in tis forward guidance, we may see the market’s hawkish expectations being verified and thus EUR getting some support. On the flip side should the bank opt for a more balanced approach, we may see EUR traders disappointed, selling the single currency.
AUD – September’s CPI rates eyed
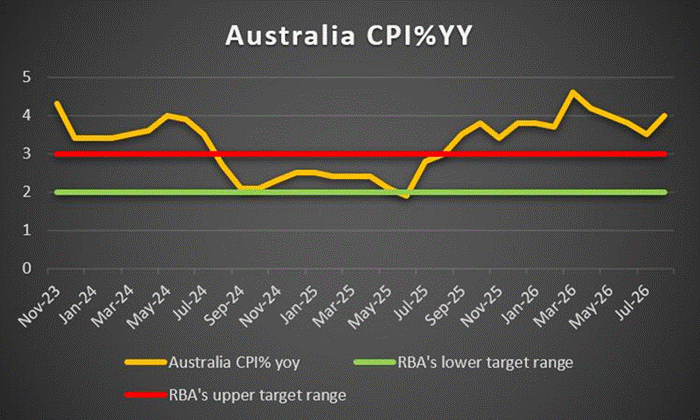
The Aussie is about to end the week in the greens against the USD halting its drop. On monetary policy level, Aussie traders expect marginally the bank to hike rates in early November meeting, a scenario that tends to be supportive for the Aussie. The market’s expectations for RBA’s intentions are to be put to the test next Wednesday, as we get Australia’s CPI rates for September. A possible acceleration of last month’s CPI rates could push them higher than 4.00%yy, definitely higher than the bank’s 1%-3% inflation target zone. Such a scenario could enhance market expectations for the RBA to proceed to a rate hike.
It’s characteristic that Reserve Bank of Australia Deputy Governor Hauser stated that the inflation outlook is materially worse than RBAs’ forecast. On a deeper fundamental level, we note that the Aussie as a commodity currency, tends to be sensitive to the market’s risk on/off tendencies. Should the market’s sentiment improve, we may see AUD getting some support as it is considered a riskier asset in the FX market and vice versa should the market sentiment turn more cautious, AUD may lose ground.
CAD – BoC expected to hike rates
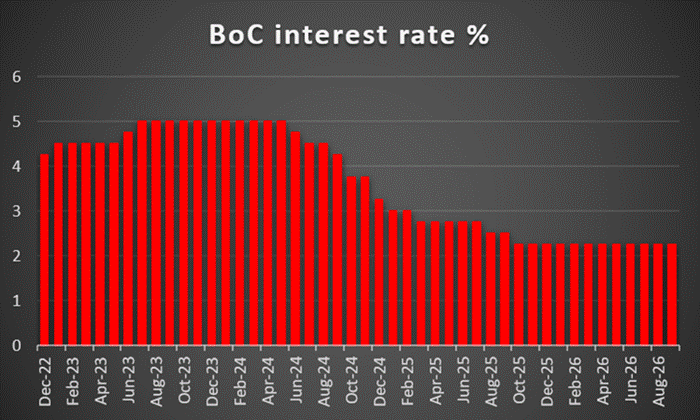
The Loonie is about to end a second week with heavy gains against the USD. As oil prices remain high, the Loonie tends to get some support on a fundamental level, given that Canada is a major oil producing economy. Yet in the coming week all eyes are expected to be on BoC’s interest rate decision. CAD OIS imply that the market is pricing in a rate hike by BoC next Wednesday, then the bank to remain on hold in December and hike rates again in January. CPI rates for September provided mixed signals by easing at a core level and accelerating slightly at a headline level.
Yet the high energy costs, tend to feed worries for inflationary pressures in the Canadian economy. We expect the bank to proceed with a rate hike, as does the market, yet the question is, whether the bank will signal more rate hikes to come. Should that be the case, we may see the Loonie getting some support. On the flip side should BoC’s forward guidance disappoint Loonie traders, we may see the rate hike turning to a dovish hike and weigh on the CAD.
Disclaimer: This information is not considered investment advice or an investment recommendation, but instead a marketing communication.


